Brian Haara
Bourbon. Law. Author.
Dog Days of Summer Hit Brown-Forman

This week saw the latest development in a 12-year legal battle between Brown-Forman and VIP Products, the maker of a novelty dog chew toy that looks like a bottle of Jack Daniels but makes all kinds of “poop jokes.”
It’s been a back-and-forth case with Brown-Forman winning twice in District Court in Arizona, losing twice at the Ninth Circuit Court of Appeals, winning once before the United States Supreme Court, and maybe heading back to the Supreme Court.
In the recent Ninth Circuit loss for Brown-Forman, the court ruled that “Bad Spaniels is a parodic dog toy not intended for human consumption,” and disagreed with the District Court, holding instead that “There is no evidence in the record from which a court could reasonably infer that scatological references made on a dog toy have the same likelihood of generating disgust as identical references on a consumable product meant for humans might.”
The Ninth Circuit (some critics call it the “Ninth Circus”) has an 86% reversal rate by the Supreme Court, so perhaps we will see another appeal by Brown-Forman hoping for another reversal.
In the meantime, the real question might be whether it surprises anyone that a poop-themed dog chew toy venture is apparently so lucrative that it can go toe-to-toe against Brown-Forman for 12 years.
.
True Story: Lawsuit Pits Two Bourbon Hall of Famers Against Each Other.
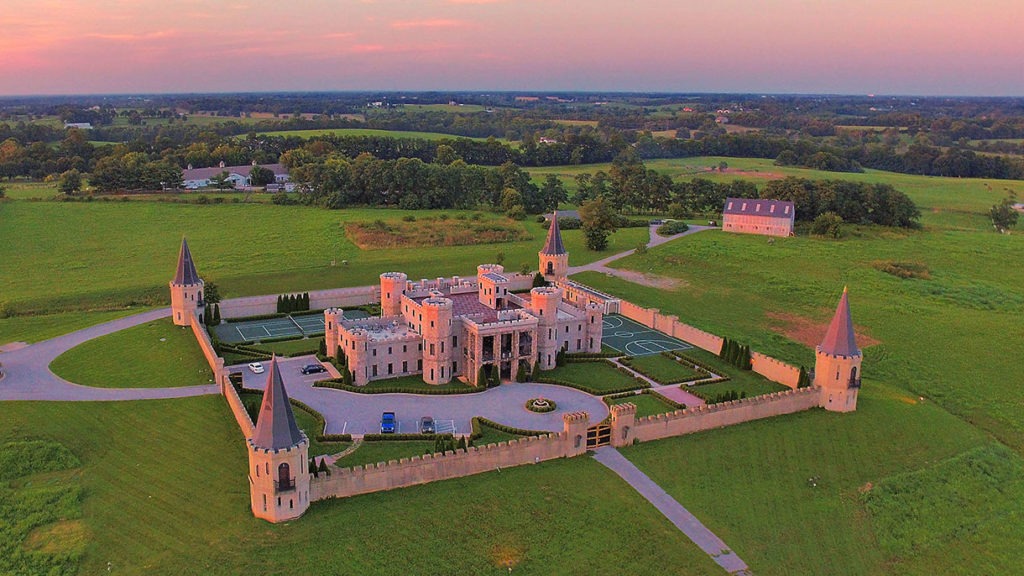
Led by its namesake Bourbon Hall of Famer, Peggy Noe Stevens & Associates has sued TKC Distilling Co. TKC probably does not sound familiar to anyone, and its assumed name, Saga Spirits Group, might not sound any more recognizable. The familiar name is the venture led by another Bourbon Hall of Famer, Wes Henderson—True Story Whiskey and the $92.5MM distillery that they’re building in Versailles at the site of The Kentucky Castle (“TKC”).
The Complaint filed in Louisville alleges that the parties entered into a Consulting Agreement covering topics like strategies, tourism, branding, and aesthetics for the overall project at The Kentucky Castle and the farm’s property-to-plate restaurant. It alleges that by October 2025, TKC was in default, and that TKC acknowledged its default.
Now Peggy is asking for a judgment over $500,000, plus reimbursement for her attorney’s fees and expenses.
Remember, Complaints only present the plaintiff’s version of events and TKC is expected to file its formal response in court in the coming weeks, where it will have the opportunity to tell Wes’s side of the story.
New Sixth Circuit Opinion: The Three-Tier System is Constitutional—Feigning Public Health Concerns to Discriminate is Not.
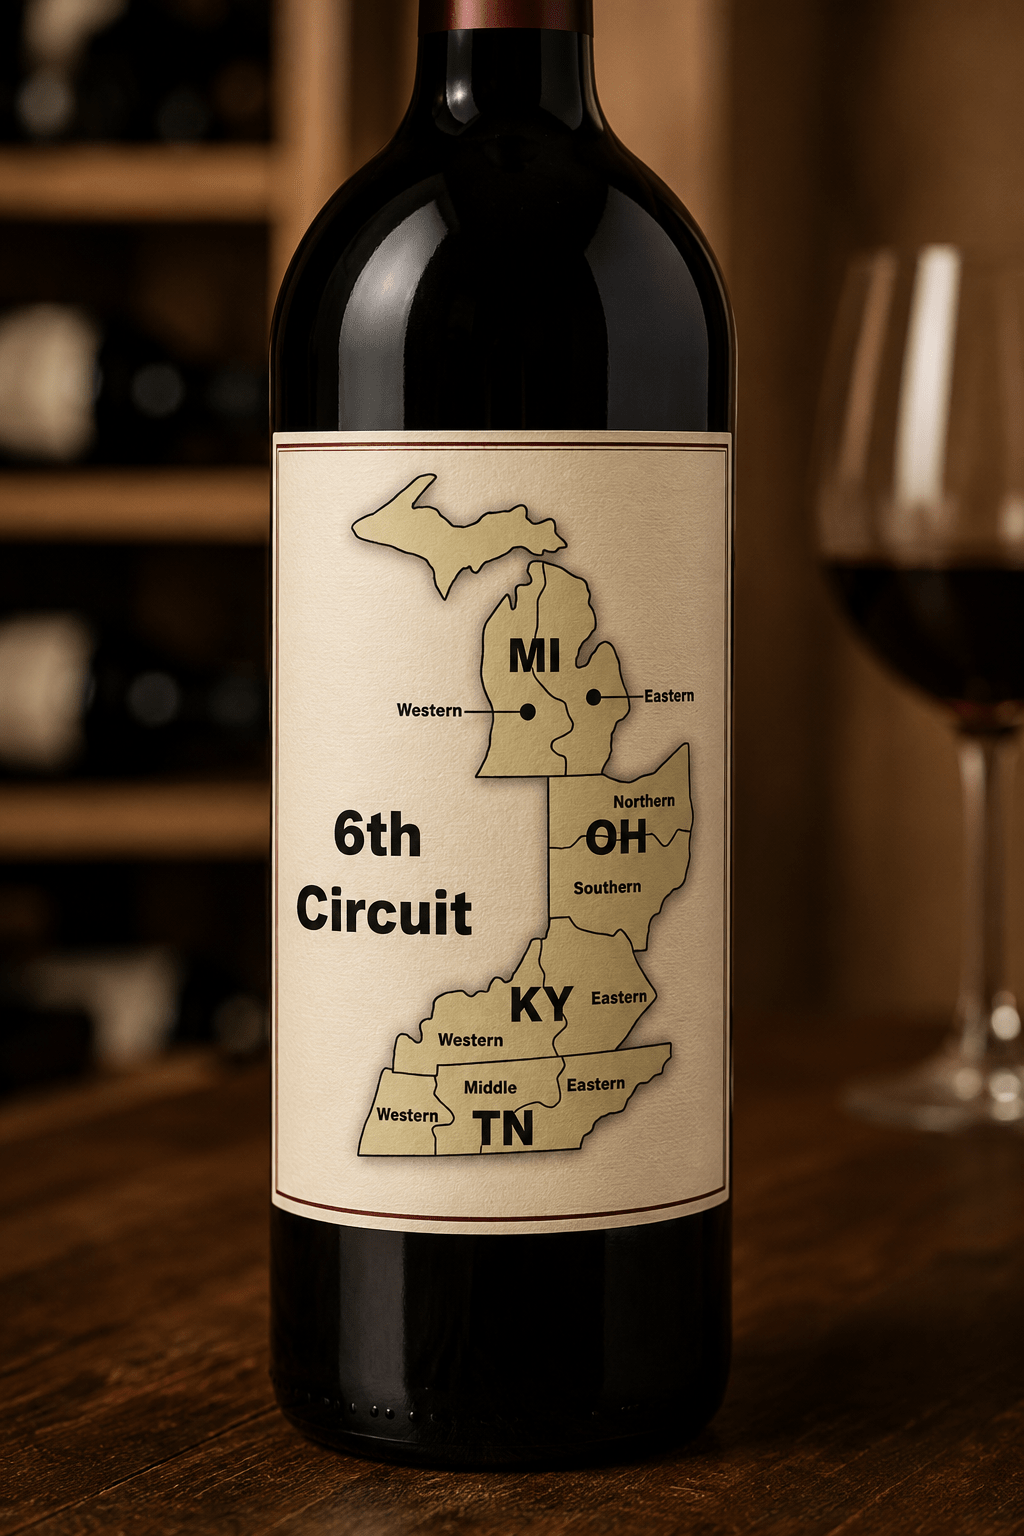
In a groundbreaking decision and major blow to interstate discrimination under the three-tier system, the Sixth Circuit Court of Appeals in Cincinnati held that Ohio’s discriminatory law prohibiting wine from being shipped to Ohio consumers from outside the state was unconstitutional. (Read Block v. Canepa here: https://www.opn.ca6.uscourts.gov/opinions.pdf/26a0132p-06.pdf).
Discrimination alone isn’t enough, because under the test established by the Supreme Court in Tennessee Wine & Spirits Retailers Assoc. v. Thomas, a discriminatory law can still be constitutional if “(1) it ‘can be justified as a public health or safety measure or on some other legitimate nonprotectionist ground,’ and if (2) its ‘predominant effect’ is ‘the protection of public health or safety,’ rather than ‘protectionism.’”
Since there was no legitimate public health or safety basis for the law, the Court stated, “It is thus clear that the predominant effect of this law is not to ensure the public health and safety, but rather to ‘deprive citizens of their right to have access to the markets of other States on equal terms,’ and instead direct them to purchase wine from Ohio retailers.”
Ohio has already filed a motion to suspend the effectiveness of this ruling to provide an opportunity for it to appeal to the Supreme Court of the United States, which it must do by August 4, 2026. The Sixth Circuit is now considering this request, with Ohio arguing that the Court’s ruling is contrary to other federal appellate court decisions.
Seven other circuits have allowed states to enforce similar physical-presence requirements, and some of those courts even ruled that similar restrictions were based on valid public-health considerations. Ohio argued that this suggests that a majority of the Supreme Court would reverse the Sixth Circuit. The circuit split increases the likelihood that the ruling will be temporarily suspended and could lead to an acceptance of the case by the Supreme Court, which would give the Supreme Court the chance to emphasize that just because the three-tier system as a whole is constitutional, it does not give states free reign to discriminate.
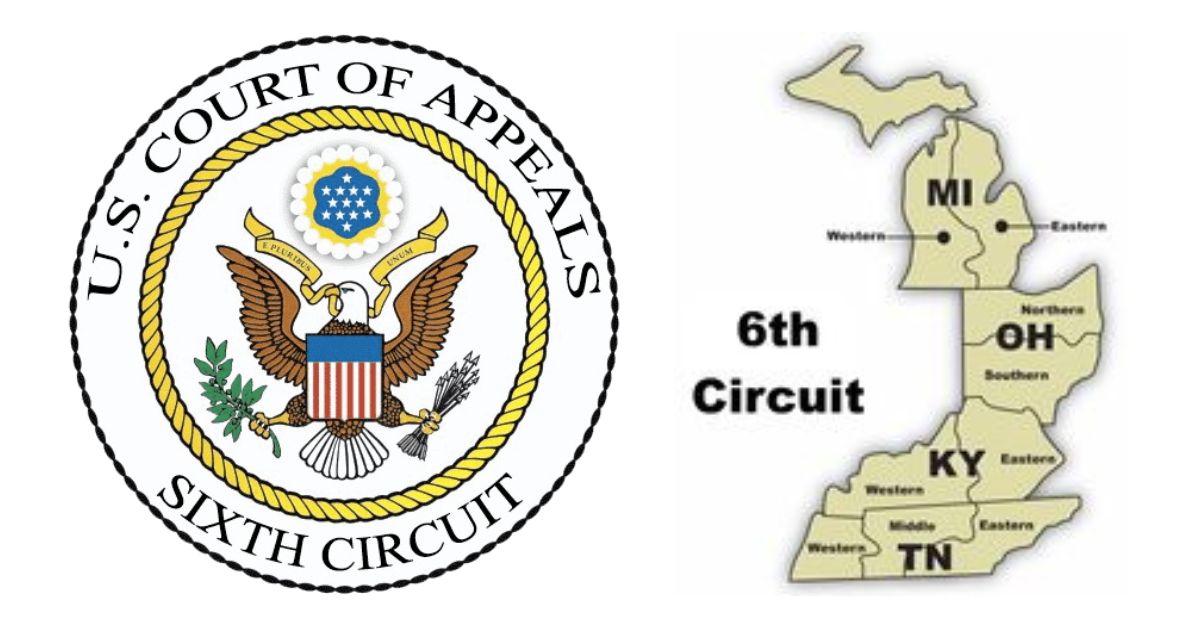
The Sixth Circuit hears appeals from Ohio, Michigan, Kentucky, and Tennessee, so if the ruling stands, shipping in those states could finally open up.
Mystery Buyer of Barrell Craft Spirits Facility Sued Over Bulk Canadian Whisky
It did not take long for the new owner of Barrell Craft Spirit’s state-of-the-art blending and bottling facility in Louisville to find itself embroiled in a lawsuit. And as a bonus, the lawsuit revealed the surprisingly low cost of Canadian Whisky.
Wyoming-based American Craft Bottling, LLC (“ACB”) bought Barrell’s facility in late January 2026 for $3,738,000.00, but since then, all media reports about the sale failed to provide any information about ACB.
What is American Craft Bottling?
Facts about ACB were not easy to find. It is a Wyoming LLC, but its filing does not list an actual place of business there. Its address, 30 N. Gould St. in Sheridan, Wyoming, is the address of a registered agent that local press has reported is connected with fraudulent or scam businesses. (Wyomingnews.com link).
Maybe showing a further disconnect with Wyoming, the executive who signed the deed for ACB didn’t sign in Wyoming; he signed in California. And other than being identified as the purchaser in the deed, ACB does not seem to have any connection with Kentucky, either.
Looking further, an entity related to ACB is the similarly-named American Craft Distillers, LLC (“ACD”). It has the same corporate information in Wyoming, and its principal address and mailing address are both the same as the registered agent—the 30 N. Gould address in Sheridan, but it is not registered with the Kentucky Secretary of State.
ACD does at least have a website: https://www.acdistillers.com/, but they did not respond to my inquiry through the website.
Even though ACB bought the property, it is ACD that claims to operate a business there. ACD claims that it “provides a comprehensive range of services throughout the spirits industry” and “specializes in contract manufacturing, research and development, regulatory compliance, and brand support.” ACD claims to have an inventory of aged whiskey in Kentucky and says that it can supply other spirits like gin, tequila, rum, and even grain neutral spirit.
Through common ownership or executives, ACB and ACD appear to be related to a company called Ethanol US LLC, which has distillery operations in Torrington, Wyoming. Another related entity appears to be LIBEX LLC, which was also organized by the same executive and listing the same address at 30 N. Gould. LIBEX, which has been dissolved, was a fund started in 2020 for investing in whiskey, which LIBEX touted as having a 10% annual growth potential.
Anderson County Distilling Company Files a New Lawsuit.
Selling whiskey barrels brings us back to the new lawsuit filed this week. Anderson County Distilling Company just sued troubled New York distiller Black Button Distilling (which was reportedly saved from bankruptcy last year by Kris Comstock-led Blackstar Company). But Anderson County also sued ACD, alleging that ACD acquired the assets of Black Button.
The lawsuit involves the alleged sale of 10 barrels of 25-year-old Canadian Whisky. Although obviously not as valuable as Kentucky Bourbon, the sale price might be the most shocking part of this story: a mere $1,200 per barrel. Anderson County alleges that it paid for the barrels but that defendants now refuse to deliver them.
What’s Next?
Remember, Complaints only present the plaintiff’s version of events and the defendants are expected to file their formal response in court in the coming weeks, where they will have the opportunity to tell their side of the story.
As with most civil lawsuits, this one will probably settle and we may never know the true result. But hopefully we will learn more about the mysterious owners from Wyoming.
Fire Up Your Home Still!?! Maybe not just yet.
Taxation has always been associated with whiskey in the United States. The nation’s first excise tax, levied in 1791, was on whiskey, and was enacted to fund the national debt incurred during the Revolutionary War. Whiskey would be taxed again to fund subsequent wars, and it was brought back permanently on August 1, 1862 to fund the Union’s efforts in the Civil War.
As Congress tinkered with the tax to address rampant fraud and tax evasion, in 1868 it prohibited distilling at home. This prohibition has remained intact for the past nearly 160 years, but has been challenged recently. April 2026 has proven to be a monumental month for those court challenges.
On April 10, 2026, in McNutt v. US Department of Justice, the Fifth Circuit Court of Appeals held that the law was unconstitutional. But on April 21, 2026, the Sixth Circuit Court of Appeals upheld the ban. This is called a “circuit split” and it could set up review by the Supreme Court of the United States.
The 1868 law prevented a person from using “any still, boiler, or other vessel for purpose of distilling” located, among other places, “in any dwelling-house.” Since 1868, the law has been amended to prohibit distillation at any home, shed, or yard, on a boat, or practically anywhere else. If you violate it, expect a fine of up to $10,000.00 and five years in prison.
The Fifth Circuit held that the government got it all wrong by prohibiting home distillation through tax laws because by outright prohibiting it, there’s obviously nothing to tax. When there’s nothing to tax, the government is not raising any revenue, which is the whole purpose of taxation. The Sixth Circuit ruled that while maybe the tax law lost revenue from home distillers, Congress also could have concluded that prohibiting distillation anywhere other than a licensed distillery actually increased tax revenue due to the likelihood of tax evasion by home distillers.
Then each court went deeper into constitutional law—a provision of the Constitution that empowers Congress to make any law “necessary and proper” to implement the powers vested in the government. In a nutshell, it is an extremely broad power to do what it takes to support other Constitutional powers, and it has been used for things such as creating a national bank, regulating the environment, or drafting soldiers.
Here again the circuits ruled differently. The Fifth Circuit ruled that banning home distillation was neither necessary nor proper to support the right of Congress to tax because it criminalizes personal conduct and prevents taxation. The Sixth Circuit considered the rampant history of tax evasion by distillers that the 1868 law sought to solve by banning home distillation, finding that the ban was necessary to be able to collect federal excise taxes on spirits.
The contrary rulings essentially leave us where we were before either of them. Operating a non-licensed still remains illegal, and the government could argue another basis for enforcement, like the Commerce Clause. We are at the very early stages of a fight that is unlikely to be resolved for another five years or so.
Should home distilling be legal? Post your comments below!
POV: coming out of the woods on April 10, and turning back around on April 21.
 Brian Haara
